Tax Tribunal says plastic preforms undergo genuine manufacturing before becoming bottles, allowing Equator Bottlers to offset excise duty.
A KSh18.4 million tax dispute has ended with a sharp defeat for the Kenya Revenue Authority.
The Tax Appeals Tribunal has ruled that plastic bottle preforms qualify as raw materials.
The decision allows Equator Bottlers Limited to offset excise duty paid on those preforms.
It also overturns KRA’s attempt to treat the materials as ordinary packaging.
The ruling, delivered in Nairobi on September 18, 2026, settles a dispute rooted in Kisumu.
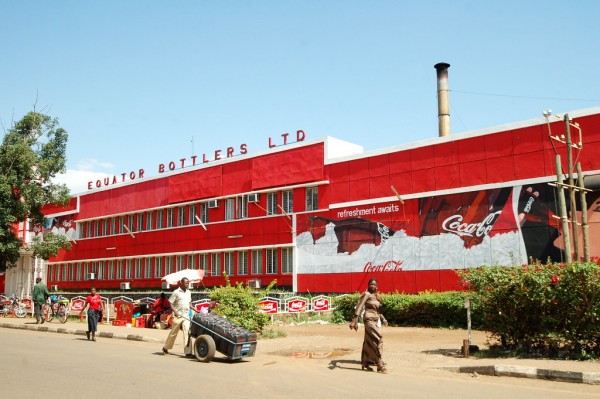
Equator operates a licensed manufacturing plant there, producing bottled water and non-alcoholic beverages.
The company buys plastic preforms from Coca-Cola Beverages Kenya Limited for its production process.
Those preforms resemble small plastic test tubes when they arrive at Equator’s facility.
They are heated, moulded and expanded under pressure before becoming finished plastic bottles.
The transformation is irreversible and produces an article with a different character and purpose.
The dispute began after Equator offset excise duty paid on preforms between April and June 2025.
KRA reviewed the company’s returns and rejected the claimed relief under Section 14(1).
It argued that preforms were packaging materials rather than raw materials used during manufacturing.
KRA subsequently issued an assessment demanding KSh18,445,951 from the Kisumu-based beverage manufacturer.
The amount included KSh17,019,636 in principal excise duty, alongside penalties and interest.
Equator objected on October 23, 2025, but KRA maintained its position in December.
Tax Fight
The Tribunal first examined whether Equator had filed its appeal within the required statutory period.
KRA argued that the company’s Notice of Appeal had arrived after the deadline.
Equator filed the notice on February 2, 2026, after receiving KRA’s December decision.
The Tribunal rejected KRA’s objection after examining how statutory time should be calculated.
It found weekends and public holidays should be excluded when computing the appeal period.
Equator’s notice therefore fell within the legally prescribed period.
That preliminary victory cleared the way for the larger battle over excise duty.
At its heart was the meaning of “raw materials” under Kenya’s Excise Duty Act.
The Act does not expressly define the term, creating room for competing interpretations.
The Tribunal instead adopted an established definition based on the role materials play.
It described the inquiry as functional rather than dependent upon an item’s outward appearance.
The Tribunal found preforms satisfied that test because they arrived semi-processed and required substantial further transformation.
More importantly, they could not perform their intended purpose in their purchased state.
Bottle Battle
KRA argued that the actual excisable product was water, with bottles merely providing containment.
The Tribunal found that interpretation incompatible with the statutory language governing bottled water.
Kenya’s Excise Duty Act specifically imposes duty on “bottled or similarly packaged waters”.
That wording, the Tribunal found, gives the bottle a significance beyond ordinary packaging.
The court consequently treated the bottle as part of the finished excisable product.
The preform therefore became a raw material because it was transformed into that bottle.
The Tribunal drew an important distinction from another tax dispute involving London Distillers.
That case concerned alcoholic beverages whose statutory definition did not depend upon their packaging.
“Water, which is not bottled or similarly packaged, is not an excisable good at all,” it held.
That distinction allowed the Tribunal to apply the London Distillers test differently here.
The Tribunal said the relevant question was whether the input became part of the final excisable product.
The preform satisfied that requirement because it became the bottle containing the finished beverage.
Kenafric Link
The Tribunal’s reasoning was also strengthened by the earlier Kenafric litigation.
That dispute similarly concerned excise duty paid on plastic preforms used in beverage production.
The Tribunal had previously ruled that such preforms qualified as raw materials under Section 14.
KRA challenged that decision before the High Court, but the challenge ultimately failed.
The High Court dismissed KRA’s appeals against the Tribunal’s Kenafric decisions on December 19, 2025.
That judgement was delivered three days before KRA issued its decision against Equator.
The Tribunal therefore found KRA could not simply disregard the existing Kenafric position.
A pending appeal, without a stay, does not automatically suspend an existing judicial decision.
The Tribunal described the Kenafric High Court judgement as directly applicable to Equator’s dispute.
It said that decision concerned “the same input and the same charge” involved here.
KRA Defeated
The Tribunal also rejected KRA’s argument that transforming preforms into bottles was not manufacturing.
Section 2 expressly includes intermediate or unfinished processes within the definition of manufacture.
The Tribunal found the preform and bottle differed in name, character, and use.
A preform cannot hold a beverage, while a finished bottle can contain and preserve one.
It therefore rejected KRA’s suggestion that the process merely changed the item’s size.
Instead, the Tribunal described the transformation as an irreversible manufacturing process.
Equator’s production line also mattered because the company does not manufacture bottles for separate sale.
It moulds them, fills them and seals them during one continuous production process.
READ ALSO: KRA Loses KSh116 Million Tax Battle Over Drifield’s Irrigation Imports
The Tribunal concluded that Equator had satisfied every statutory requirement for the excise-duty relief.
It found the company was “squarely within” the terms of Section 14(1).
The Tribunal consequently allowed Equator’s appeal and set aside KRA’s December 22 decision.
It ordered each party to bear its own costs, bringing the Sh18.4 million dispute to an end.
The ruling leaves a significant message for Kenya’s beverage manufacturers and tax administrators.
Where an excisable input undergoes substantial transformation, its role cannot be dismissed as mere packaging.
For Equator, that distinction has now translated into a decisive legal and financial victory.
PAY ATTENTION: Reach us at info@gotta.news.